Most people who buy life insurance name one person — usually a spouse — and never think about it again. That leaves a gap. If that person dies before you, cannot be found, or refuses the benefit, who gets the money? A contingent beneficiary answers that question. It is the backup you name on the same form, standing behind your primary beneficiary, so the payout still goes where you intended instead of falling into your estate. If you are still deciding how much cover you need, start with our guide to life insurance cost in the USA by age, then come back and make sure the payout reaches the right hands.
What Is a Contingent Beneficiary?
A contingent beneficiary — also called a secondary beneficiary — is the person, trust, charity, or organisation you name to receive the death benefit if every primary beneficiary is unable to collect it. Fidelity puts it plainly: it is the person or entity who would inherit your assets if your primary beneficiary can’t or declines. The National Association of Insurance Commissioners (NAIC) agrees: secondary beneficiaries receive proceeds if a primary beneficiary dies before you.
The key point is the order: the backup is second in line, not a co-recipient, and only steps in when every primary beneficiary is out of the picture. You can name almost anyone as a contingent beneficiary — a child, sibling, parent, friend, charity, or trust — using full legal names so the insurer can find them.
Primary vs Secondary Beneficiary: How the Two Layers Work
Think of the two layers as a first team and a backup team. The primary beneficiary is first in line; the backup waits behind them and only plays if the whole first team is unavailable.
| Feature | Primary beneficiary | Backup (secondary) beneficiary |
|---|---|---|
| Position | First in line for the death benefit | Second in line |
| When they are paid | When you die, if they outlive you and can receive the money | Only if every primary beneficiary has died, cannot be found, or refuses the benefit |
| If one of several primaries survives | The surviving primaries share the payout | Receives nothing |
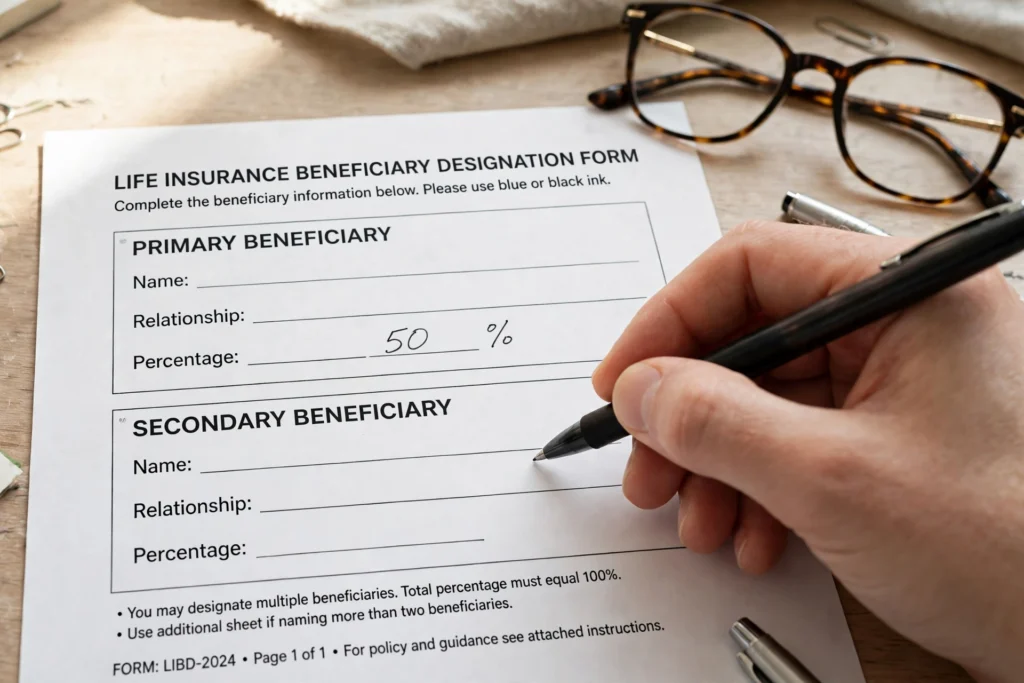
A contingent beneficiary is paid when the primary beneficiary has died before you, cannot be located, or formally refuses — disclaims — the benefit. A rarer trigger is legal disqualification: every state has some form of “slayer rule” that bars a beneficiary who intentionally killed the policyholder. If you and your primary die together and the order of death cannot be determined, most states require the beneficiary to have survived by at least 120 hours — five days. Naming a backup gives that person no rights while you are alive: they cannot change the policy or borrow against it.
When Should You Name a Contingent Beneficiary?
The short answer is: always, on every policy. Spouse as primary, children as backup is the most common setup: your spouse receives 100% if they outlive you, and your adult children split the benefit equally if your spouse has already died.
Divorce and remarriage are when designations most often go wrong. In many states a divorce automatically revokes a former spouse’s designation, but not everywhere — an ex-spouse can still receive the benefit if they remain the valid beneficiary on file. After a divorce or remarriage, review the policy directly with the insurer and name a new primary and backup.
Minor children need special care: insurers generally will not pay a death benefit directly to a child under 18 — 21 in a few states. Without an arrangement in place, the insurer holds the money until a custodial account under your state’s Uniform Transfers to Minors Act (UTMA) or a court-appointed guardian is arranged, and the court route is slow, public, and expensive. Better options are naming a trust as the backup, or a custodian under UTMA for a smaller policy. Single parents usually name their children as primary beneficiaries in equal shares and a sibling, parent, or trust as backup. Never leave the contingent beneficiary line blank.
How to Split the Benefit by Percentage
When you name more than one person at the same level, assign each a percentage, and the percentages at each level must add up to exactly 100% — primary and backup layers are calculated separately. You need not split equally: three contingent beneficiaries could each receive about 33.3%, or one 50% and the other two 25% each. Percentages beat fixed dollar amounts, because the final payout can change.
Per stirpes means “by branch”: if a beneficiary dies before you, their share passes down to their children. Per capita means “by head”: the share is redistributed equally among the survivors. A revocable beneficiary can usually be changed at any time; an irrevocable one usually needs their consent.
How to Change Your Beneficiary
Changing a beneficiary is a formal process, but a short one. A will, a verbal instruction, a handwritten note, or an unsigned form does not change it — the insurer pays according to the valid designation on file, not instructions in your will. Get the insurer’s change form from its portal, your agent, or customer service (from HR for group cover). Fill in each person’s details and percentage, submit the signed form, and keep written confirmation. The old designation stays in force until the new one is accepted. Review the designation after every major life event and repeat the review every year.
What Happens If You Name No Backup?
If your primary beneficiary dies before you and you never named a contingent beneficiary, the death benefit usually defaults to your estate. From there it enters probate — the court process for handling a person’s property after death — and is distributed under your will, or under your state’s intestacy laws if you left no will.
That costs your family in three ways. First, it is slow: probate takes months, while a named beneficiary is usually paid directly once the claim is approved. Second, money paid to the estate is exposed to creditor claims and estate expenses. Third, it may not go where you wanted: intestacy laws follow a fixed order — typically spouse, then children, then parents. The insurer also does not pay automatically: beneficiaries must file a claim — contact the insurer, complete a claim form, and provide a certified death certificate. Straightforward claims are often completed within several weeks. Tell your beneficiaries where the policy is.
Common Mistakes to Avoid
The most common mistakes are leaving the contingent beneficiary line blank, naming a minor child directly with no trust or custodian, forgetting to update the form after divorce or remarriage, entering percentages that do not total 100%, assuming a will changes the policy, and naming your estate as beneficiary.
Frequently Asked Questions
What is a contingent beneficiary in life insurance?
It is the backup person or entity named on a life insurance policy who receives the death benefit only if every primary beneficiary has died, cannot be located, or refuses the benefit.
Can I name more than one backup beneficiary?
Yes. You can name several contingent beneficiaries and split the benefit between them by percentage. The percentages for the backup layer must add up to exactly 100%, calculated separately from the primary layer’s percentages.
Can a minor child be named as a beneficiary?
A minor can be named, but insurers generally will not pay a death benefit directly to a child under 18 — 21 in a few states. The money is held until a custodian, guardian, or trust is in place; naming a trust as the backup is usually the better option.
How do I change my beneficiary?
Use your insurer’s beneficiary change form or online process — a will or phone call does not change it. Fill in each person’s details and percentage, submit the signed form, and keep written confirmation.
Does my will override my life insurance beneficiary?
No. The insurer pays according to the valid beneficiary designation on file, not instructions in a will. Keep your will, trust, and policy records coordinated, but update the policy directly when your intended recipient changes.
The Bottom Line
The backup line on a life insurance form is small, but its job is large: it makes sure your payout reaches the people you chose. Name a primary and at least one contingent beneficiary, split by percentages totalling 100% at each level, and review the form after every major life event.
Disclaimer: This article is general information about life insurance beneficiaries in the United States in 2026. It is not legal, tax, or financial advice, and it is not a personal insurance recommendation or a quote. Beneficiary rules, probate procedures, and the age of majority vary by state, and individual policies may have their own terms. Always check your policy documents and, for trusts, divorce, or complex family situations, consult a licensed insurance agent or an attorney before you decide.