Life insurance shopping is confusing enough without the jargon. Level term life insurance is the simplest policy most Americans buy — and usually the cheapest way to protect a family. Your premium stays the same every month, your payout stays the same, and the coverage lasts for a set number of years. If you die during that term, your family gets the full amount. If you outlive it, the policy ends.
This guide explains what level term life insurance is, what it costs in 2026, its pros and cons, and how it compares to decreasing term and whole life — so you can decide if it fits your family.
What Is Level Term Life Insurance?
Level term insurance is a type of term life insurance in which both the premium and the death benefit stay fixed — “level” — for the entire term you choose, usually 10, 20, or 30 years. Buy a $500,000, 20-year level term policy at age 40 and your family receives $500,000 whether you die in year one or year nineteen, while your monthly payment never changes.
That predictability is the whole point. Your mortgage payment does not change, your income needs do not shrink on a schedule, and your children’s college costs do not fall each year — so a payout that stays constant matches real life. Most people who say “term life insurance” mean level term life insurance: it is the default, most popular form of term coverage in the United States.
It has no cash value and no investment component. You are buying pure protection for a set period. That is exactly why it costs so much less than permanent insurance — every dollar of premium goes toward the death benefit, not toward building savings inside the policy.
How Much Does Level Term Life Insurance Cost in 2026?
Age drives the price more than any other factor. The table below shows NerdWallet’s 2026 average annual rates for a $500,000, 20-year level term policy for preferred applicants in good health who do not smoke (data from LifeStein.com, valid as of October 1, 2026), converted to monthly figures.
| Age | Women (per month) | Men (per month) |
|---|---|---|
| 20 | $15 | $17 |
| 30 | $15 | $18 |
| 40 | $23 | $27 |
| 50 | $53 | $68 |
| 60 | $137 | $195 |
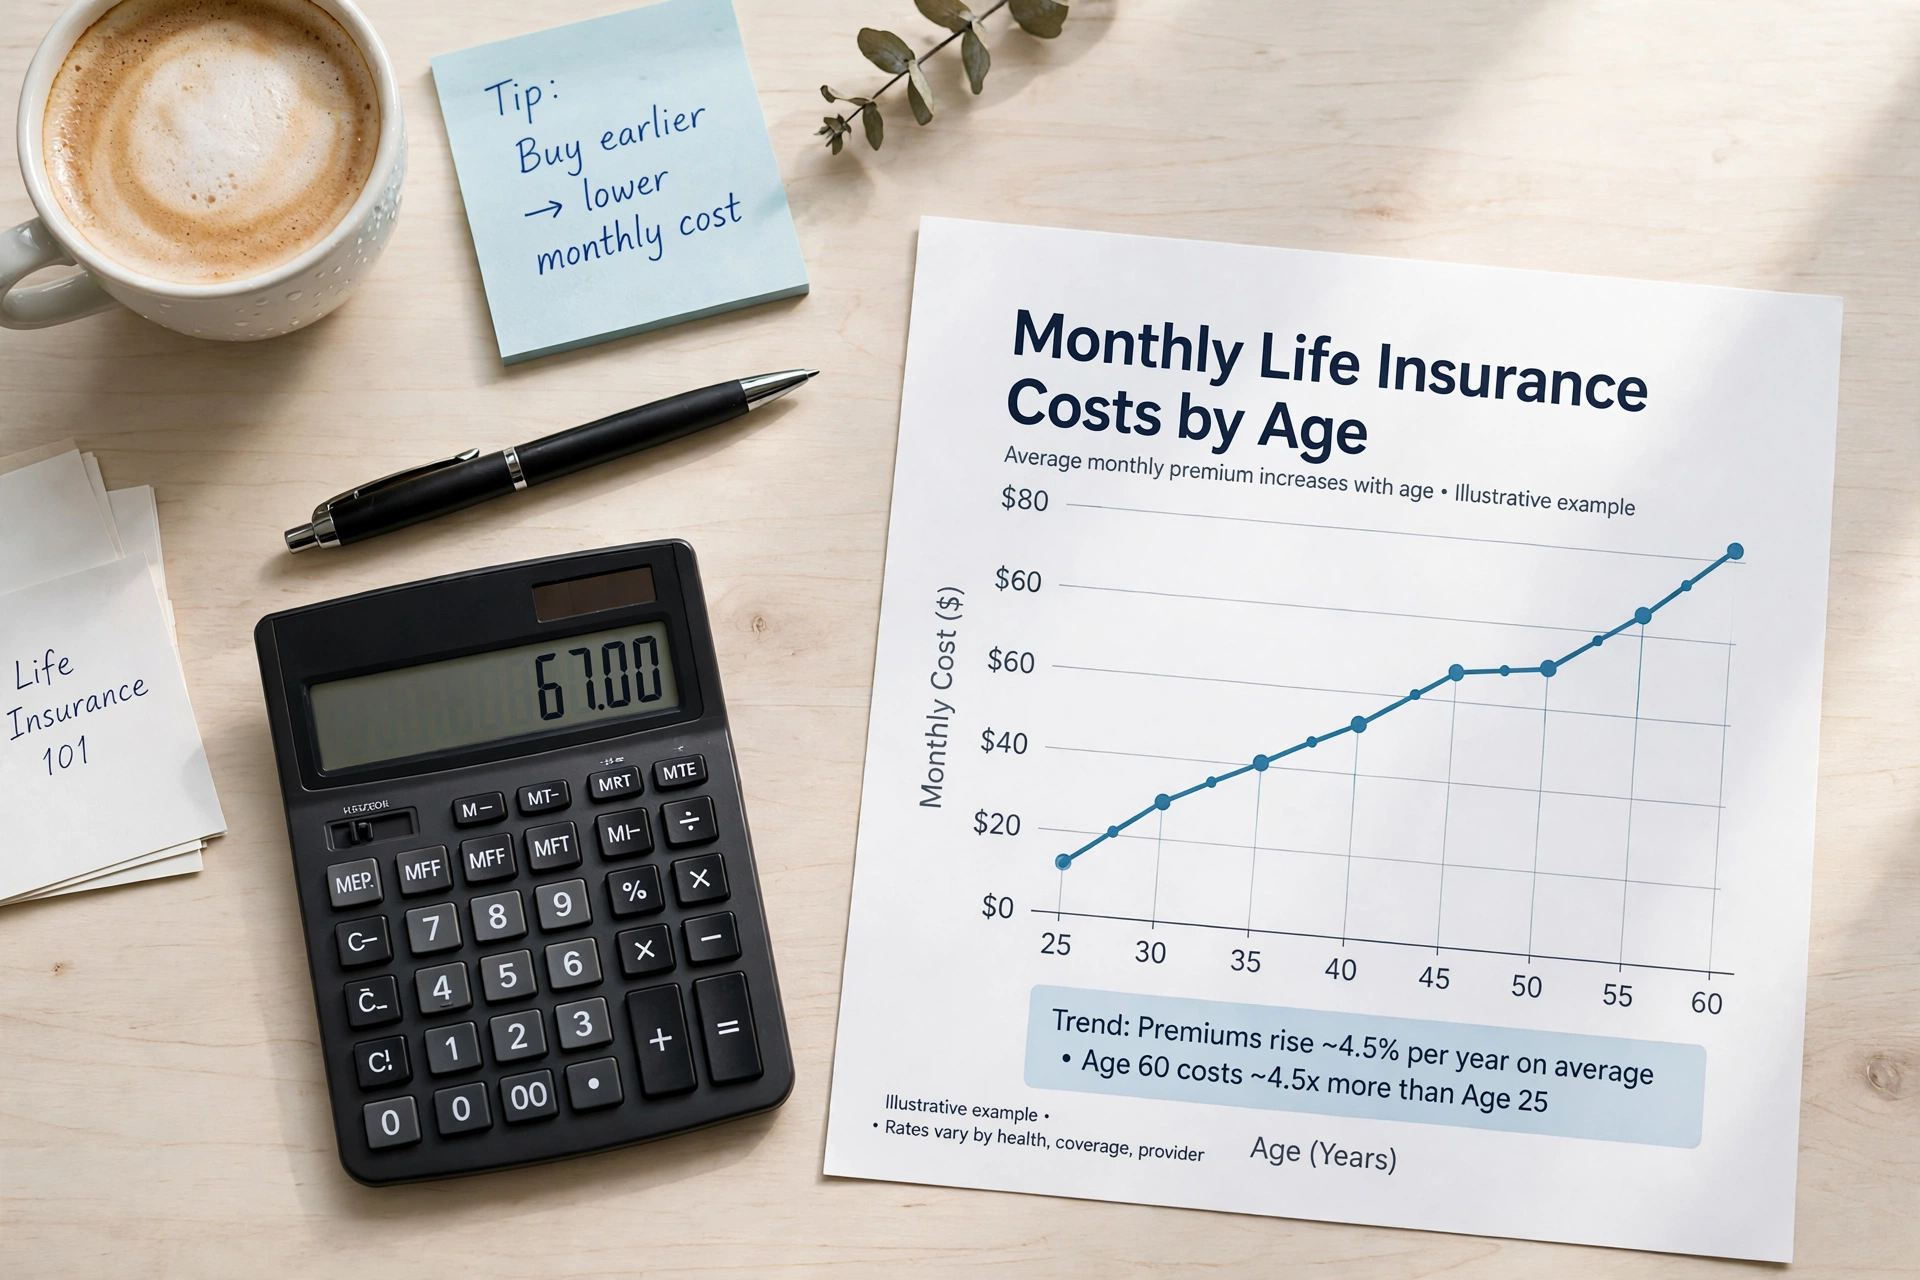 A healthy 40-year-old pays about $23 to $27 a month for half a million dollars of coverage — less than a daily coffee. But wait ten years and the same policy costs roughly three times as much, and at 60 it costs about six to seven times as much. That is the single most important fact about term life: buying young locks in a low rate for the whole term.
MoneyGeek’s 2026 analysis, which uses average health rather than preferred health, shows slightly higher figures: a 40-year-old pays about $37 a month (women) or $44 a month (men) for the same $500,000, 20-year policy, and $65 to $80 a month for $1 million of coverage. The gap between the two sources is the health class — preferred applicants pay less than average-health applicants for identical coverage.
What else affects your price?
- Smoking: the largest controllable cost. A 40-year-old smoker pays about $119 a month (women) or $154 a month (men) for a $500,000, 20-year policy, according to MoneyGeek — roughly three times the nonsmoker rate.
- Health class: preferred plus, preferred, standard plus, and standard. A 40-year-old woman pays about $30 a month at preferred plus versus $52 at standard for the same policy.
- Term length: longer terms cost more per month. For a 40-year-old, a $500,000 policy costs about $17 a month for 10 years, $27 for 20 years, and $48 for 30 years (men, NerdWallet annual figures divided by 12).
- Coverage amount: a $1 million policy costs more than a $500,000 one, but the cost per $1,000 of coverage falls as the amount rises.
- Gender: women pay less than men at every age because of longer average life expectancy.
For a full breakdown of how life insurance costs change with age, see our guide to life insurance cost in the USA by age.
Pros of Level Term Life Insurance
- Affordable: the cheapest way to buy a large death benefit. A healthy 40-year-old can protect their family with $500,000 of coverage for about $26 a month on average.
- Predictable: your premium and your payout never change during the term, which makes family budgeting simple.
- Simple: no cash value, no investment choices, no confusing fees — just a fixed price for fixed protection.
- Flexible term lengths: choose 10, 20, or 30 years to match your mortgage, your children’s dependency, or your working years.
- Convertible: many level term policies let you convert to a permanent policy later without a new medical exam, which matters if your health changes.
Cons of Level Term Life Insurance
- It expires: if you outlive the term, coverage ends and you get nothing back. A 20-year policy bought at 40 leaves you uninsured at 60, right when a new policy would be expensive.
- No cash value: unlike whole life, you cannot borrow against it or surrender it for money.
- Premiums rise if you renew: renewing after the term ends — or buying a new policy at an older age — costs far more. A 60-year-old pays about $195 a month for the policy a 40-year-old gets for $27.
- Inflation erodes the payout: a $500,000 death benefit fixed in 2026 will buy less in 2046. The payout does not grow with the cost of living.
- No payout if you outlive it: this is the trade-off for the low price, and it surprises some buyers.
Level Term vs Decreasing Term vs Whole Life
It is one of three common choices. Here is how they compare.
| Feature | Level term | Decreasing term | Whole life |
|---|---|---|---|
| Death benefit | Fixed for the whole term | Shrinks over time | Fixed for life |
| Premium | Fixed for the whole term | Usually fixed | Fixed for life |
| Coverage length | 10, 20, or 30 years | 10, 20, or 30 years | Lifetime |
| Cash value | None | None | Yes, grows over time |
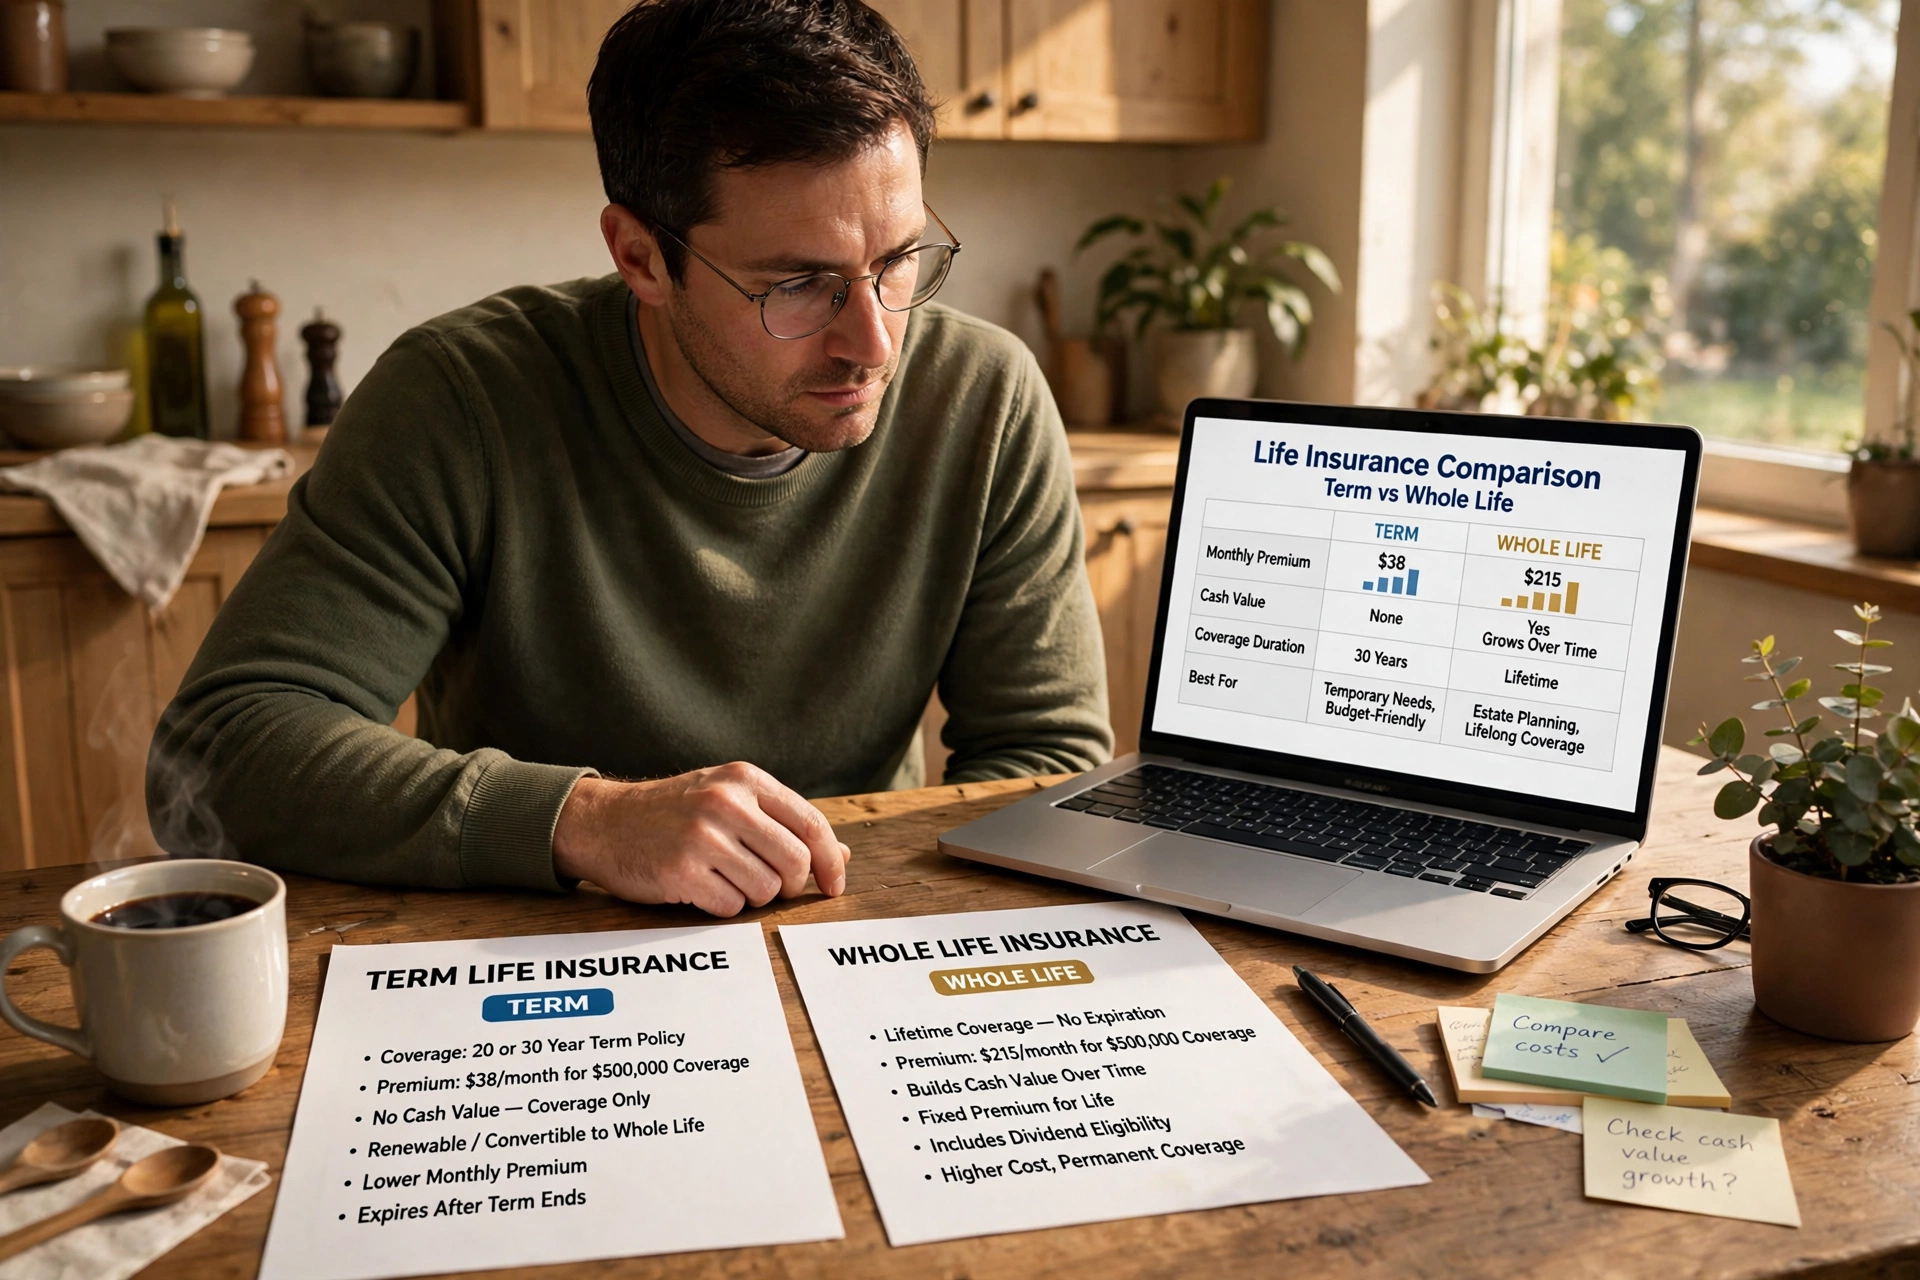
| Cost for a healthy 40-year-old, $500,000 | ~$23–$27/month | Less than level term | ~$237–$265/month |
| Best for | Income replacement, family protection | Repayment mortgage only | Lifetime cover, estate planning |
 Decreasing term is designed for one job: paying off a repayment mortgage. As you pay the mortgage down, the payout falls with it, so the insurer charges less. It is cheaper than level term, but it only covers the mortgage — not lost income, childcare, or college. If your family needs more than a paid-off house, decreasing term is not enough.
Whole life lasts your entire life and builds cash value, but the price is steep. NerdWallet’s 2026 data puts a $500,000 whole life policy at about $3,180 a year for a healthy 40-year-old man and $2,849 for a woman — roughly ten times the cost of level term. Whole life makes sense for lifetime obligations, such as estate taxes or a dependent who will always need support. For most working families, level term life insurance gives far more protection per dollar.
Who Should Buy Level Term Life Insurance?
It is the right choice for most people with temporary financial obligations:
- Parents with young children who need income replacement until the kids are independent.
- Homeowners with a mortgage who want the loan paid off plus income for the surviving spouse — not just the mortgage, which is where decreasing term falls short.
- Young workers on a budget who need a large death benefit for the lowest possible monthly cost.
- Anyone covering a fixed period, such as the years until retirement or until a business loan is repaid.
It is the wrong choice if you need coverage that can never expire, want to build cash value, or need insurance for estate planning. In those cases, whole life or universal life may fit better despite the higher cost.
How to Choose the Right Term Length
Match the term to the obligation you are protecting. A 30-year mortgage and young children point to a 30-year term; a mortgage with 15 years left and teenage children point to a 15- or 20-year term. A longer term costs more per month, but it is almost always cheaper than buying a short term now and a new policy later at an older age, when rates have risen.
Three practical tips before you buy: compare quotes from at least three insurers, because the same profile can be priced very differently; take the medical exam if you are healthy, since no-exam policies cost more; and check the conversion option, so you can switch to permanent coverage later without proving your health again. For current rate tables by age and term length, see NerdWallet’s average life insurance rates for 2026 and MoneyGeek’s term life insurance cost guide.
Frequently Asked Questions
What does level term insurance mean?
It means your premium and your death benefit stay the same — level — for the entire term, usually 10, 20, or 30 years. A $500,000 policy pays $500,000 whether you die in year one or year nineteen.
How much is level term insurance per month?
A healthy 40-year-old nonsmoker pays about $23 to $27 a month for a $500,000, 20-year level term policy at preferred rates (NerdWallet 2026), or $37 to $44 at average health (MoneyGeek 2026). Younger buyers pay less; smokers pay roughly three times more.
Is level term or decreasing term better?
Level term is better for most families because the payout never shrinks, so it covers income replacement as well as the mortgage. Decreasing term is cheaper but only covers a shrinking debt, usually a repayment mortgage.
What happens when my level term policy ends?
Coverage stops and nothing is paid. You can renew at a much higher rate, buy a new policy, or convert to permanent coverage if your policy includes a conversion option — check before the term ends.
Is level term insurance worth it?
For most working families, yes. It is the cheapest way to buy a large death benefit during the years your family depends on your income. It is not worth it if you need lifelong coverage or want cash value — then whole life fits better.
Disclaimer: This article is for general information only and is not financial advice. Rates shown are published sample averages for stated ages, amounts, and health profiles — not quotes, and not a guarantee. Your actual premium will vary by insurer, health, and underwriting. Consult a licensed insurance agent before buying a policy.
Sources: NerdWallet — Average Life Insurance Rates for 2026 | MoneyGeek — How Much Does Term Life Insurance Cost? (2026 Rates)