A single phishing email can shut down a small business for days. A ransomware attack can lock every file you own until you pay — or rebuild from scratch. A data breach can leave you paying for customer notification, credit monitoring, legal fees, and fines for years. Cyber liability insurance for small business exists for exactly these moments, and it costs far less than most owners expect: small businesses pay an average of $129 per month, or about $1,552 a year. This guide explains what cyber liability insurance for small business covers, what it costs in 2026, who needs it, and how to get the best price.
What Is Cyber Liability Insurance for Small Business?
Cyber liability insurance — also called cyber insurance or cybersecurity insurance — is a policy that helps a small business recover financially after a cyberattack or data breach. It pays for the costs that follow an incident: notifying affected customers, providing credit monitoring, hiring forensic experts, restoring hacked systems, covering lost income while you are shut down, and defending you if a customer or client sues.
It is not the same as general liability insurance, which covers bodily injury, property damage, and advertising injury — not a hacker stealing your customer database or ransomware encrypting your files. For businesses that store customer information, take card payments, or rely on software, that gap is now one of their largest risks.
Cyber liability insurance for small business is not required by law in most states, but clients, vendors, and partners — especially larger companies — often ask for proof of cyber coverage before signing a contract, and some professions need a policy simply to win work.
Cyber Liability Insurance for Small Business: What Does It Cost in 2026?
According to Insureon, which bases its figures on the median cost of policies sold to its small business customers, cyber liability insurance for small business costs an average of $129 per month, or $1,552 per year. Annual premiums typically range from $400 to over $8,000 per year, depending on the business. The distribution is encouraging for small owners: 41% pay less than $100 per month, and another 26% pay between $100 and $200 per month. Policies can start as low as $35 per month, and the typical policy carries a $1 million per-occurrence limit, a $1 million aggregate limit, and a deductible of $1,000 to $2,500.
Your industry matters a lot when pricing cyber liability insurance for small business. Businesses that handle large amounts of sensitive data or operate in high-risk sectors pay more, while low-risk businesses pay less.
| Business Type | Average Monthly Premium |
|---|---|
| Finance businesses | $59 |
| Home-based businesses | $64 |
| Retailers | $58 |
| All small businesses (average) | $129 |
| Software developers | $124 |
| IT consultants | $128 |
| IT businesses (general) | $179 |
 These figures come from Insureon’s customer data, which covers mostly businesses with fewer than five employees, annual revenue between $50,000 and $200,000, and five years or less in operation. A larger business, or one handling health records or financial data, will typically pay more. But the pattern is clear: for most small businesses, cyber liability insurance for small business costs less per month than a single employee’s phone plan.
What Affects Your Premium?
Several factors determine what you will actually pay:
- Amount of sensitive data handled. Storing credit card numbers, Social Security numbers, or health records raises your premium. A healthcare facility with many patients pays more than a small medical office with few.
- Industry risk. Tech, finance, healthcare, and retail face higher exposure than most other sectors.
- Number of employees. Every employee with access to sensitive systems is a potential entry point — often through a phishing email. More employees usually means a higher premium.
- Coverage limits and deductible. Higher limits cost more; a higher deductible lowers the premium, but only choose an amount you can actually afford to pay during a crisis.
- Cybersecurity measures in place. Firewalls, multi-factor authentication, regular software updates, and employee training can lower your rate, because they lower your risk.
- Claims history. A prior cyber claim signals higher risk to underwriters and can push your premium up at renewal.
What Does Cyber Liability Insurance Cover?
Cyber policies are usually split into two parts — understanding the difference helps you buy the right coverage instead of discovering a gap after an attack.
First-Party Coverage
First-party coverage — sometimes called data breach insurance — pays for your own business’s losses from a cyber incident. It typically covers:
- Notifying customers of a data breach, as required by state laws
- Credit monitoring services for affected individuals
- Data recovery, including forensic investigation and system restoration
- Ransomware and cyber extortion payments
- Crisis management and public relations help to repair your reputation
- Lost income during business interruption while systems are down
Third-Party Coverage
Third-party coverage pays when someone else sues your business over a cyber incident. If a client claims your company caused or failed to prevent a data breach at their business, third-party coverage pays for lawyers’ fees, settlements, and court-ordered judgments. This is especially important for businesses that handle client data, such as accountants, consultants, and IT service providers — a breach on your side can become a lawsuit from your client’s side.
What Is Usually Not Covered
Standard cyber policies generally do not cover events that happened before the policy started, criminal acts by the owner, or infrastructure failures unrelated to a cyber incident, such as a power outage. IT businesses often need tech errors and omissions (tech E&O) coverage as well, since a failure in their own product is a different kind of claim.
Who Needs Cyber Liability Insurance?
The honest answer is: almost any small business that uses a computer, takes card payments, stores customer information, or relies on software. According to Verizon’s 2021 Data Breach Investigations Report, 46% of all cyber breaches impact businesses with fewer than 1,000 employees — smaller businesses are often easier targets because they have fewer defenses. Industry data cited by Insureon adds that 43% of data breaches involve a small company, and 98% of cyber insurance claims come from small and mid-sized businesses.
You should treat cyber liability insurance for small business as a priority if your business:
- Handles sensitive customer data — names, addresses, Social Security numbers, credit card details, or health information (accountants, therapists, retailers, and brokers are prime examples)
- Operates in a regulated industry — healthcare, finance, and legal services face strict breach notification rules and fines
- Relies on e-commerce or online platforms — an attack that takes your store offline stops your revenue immediately
- Offers technology services or products — software companies, IT consultants, and managed service providers face both first-party and third-party exposure
- Has employees working remotely — home networks and personal devices widen the attack surface
Even a business with no customer data can suffer: ransomware can encrypt your own files and stop you working for days, and business interruption coverage is what pays for that lost income.
What a Breach Really Costs a Small Business
The premium looks small next to the cost of an incident. Insureon reports that the average cost of a small business data breach ranges from $120,000 to $1.2 million. IBM’s Cost of a Data Breach Report 2025 puts the global average at $4.44 million and the U.S. average at a record $10.22 million. Ransomware is the sharpest threat: IBM found the average cost of a ransomware incident disclosed by an attacker reached $5.08 million in 2025, and 63% of victims refused to pay.
Perhaps the starkest statistic comes from industry reporting cited by Insureon: most small businesses that suffer a major cyberattack close within six months — not because the attack is unsurvivable, but because the costs arrive all at once: notification, legal fees, lost income, and reputational damage, with no revenue coming in. A policy costing about $129 a month exists precisely to break that chain. For a broader view of how business liability limits work, see our guide to excess liability insurance — when a $1 million cyber limit is not enough, excess coverage can add protection above it.
How to Lower Your Cyber Insurance Premium
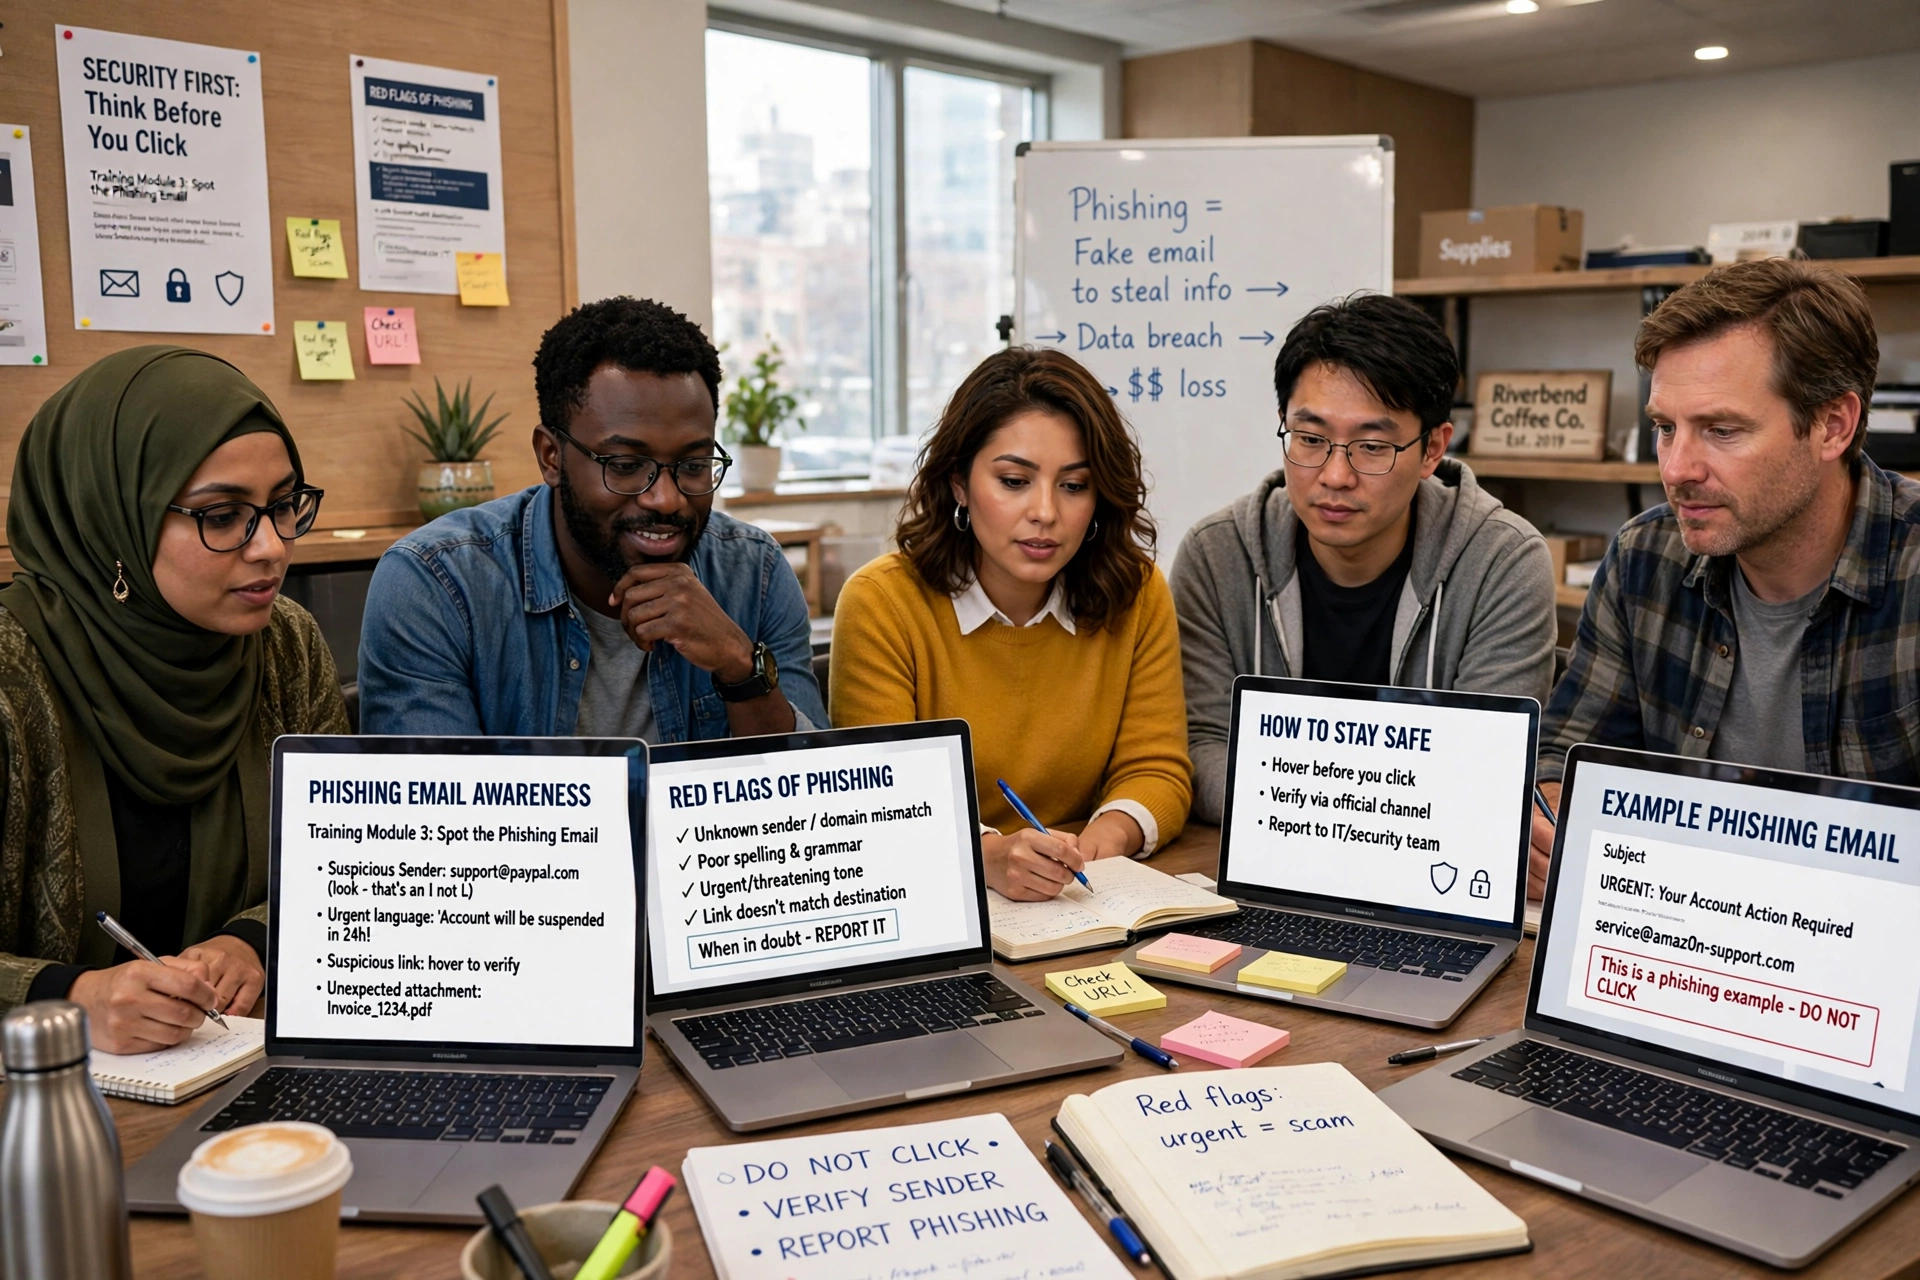 Cyber insurance premiums have stabilized and even fallen in recent years as more carriers entered the market and businesses improved their defenses. These steps can lower what you pay — and they make an attack less likely in the first place:
- Turn on multi-factor authentication (MFA). This is the single most effective cheap control. Underwriters ask about it directly, and businesses without MFA pay more — or get declined.
- Train employees to spot phishing. Most breaches start with one employee clicking a malicious link — regular, short training reduces that risk more than any software purchase.
- Keep software updated and use firewalls. Unpatched software is one of the most common entry points. Automatic updates and a properly configured firewall close it.
- Back up data offline and test the restore — ransomware only works if you cannot recover your files.
- Bundle your policies. Adding cyber coverage to a general liability policy or a business owner’s policy, or bundling it with tech E&O, usually costs less than buying standalone coverage.
- Pay the annual premium upfront. Many insurers offer a discount for paying the full year at once instead of monthly installments.
- Compare at least three quotes. Premiums for the same business can vary widely between carriers, so shopping around is worth the hour it takes.
How to Buy Cyber Liability Insurance in 5 Steps
- Take stock of your data: what sensitive information you store, where it lives, and who can access it. This determines how much coverage you need.
- Choose your limits. A common starting point is $1 million per occurrence and $1 million aggregate, with a deductible of $1,000 to $2,500. Businesses handling health or financial data should consider higher limits.
- Check what your contracts require — clients and partners may specify minimum cyber limits, so buy to the highest requirement, not the lowest.
- Compare quotes from multiple carriers. Use an independent broker or online marketplace to compare at least three options on price, limits, and exclusions — not price alone.
- Put the security controls in place first — MFA, backups, and training done before you apply can mean a lower quote and fewer exclusions. Keep records; underwriters will ask.
Frequently Asked Questions
How much does cyber liability insurance cost for a small business?
Small businesses pay an average of $129 per month for cyber liability insurance for small business, or $1,552 per year, according to Insureon’s 2026 customer data. Annual premiums range from $400 to over $8,000, but 41% pay less than $100 per month.
Is cyber insurance required for small businesses?
It is not required by law in most states, but many clients, vendors, and partners require proof of cyber coverage before signing contracts. Some professions, such as cybersecurity consultants, may need it to win work at all.
What is the difference between first-party and third-party cyber coverage?
First-party coverage pays for your own losses — notification, credit monitoring, data recovery, ransomware payments, and lost income. Third-party coverage pays when a client or customer sues you over a breach, covering legal fees, settlements, and judgments.
Does cyber insurance cover ransomware?
Yes, most cyber policies cover ransomware, including extortion payments, forensic investigation, data restoration, and business interruption losses. Check whether your policy covers the ransom payment itself and any conditions attached.
Does general liability insurance cover cyberattacks?
No. General liability covers bodily injury, property damage, and advertising injury. It does not cover data breaches, ransomware, or cyber extortion. You need a separate cyber liability policy for those risks.
Disclaimer: This article is for general information only and is not insurance advice. Premium figures are market averages from Insureon as of 2026 and will vary by business, industry, location, and carrier. Breach cost figures come from IBM’s Cost of a Data Breach Report 2025 and Verizon’s Data Breach Investigations Report. Always compare quotes and speak with a licensed insurance professional before buying coverage.
Sources: Insureon, “Cyber Insurance Cost” | Insureon, “Who Needs Cyber Insurance?” | IBM, “Cost of a Data Breach Report 2025”