If your small business cannot afford a traditional group health plan, you are not out of options. With health reimbursement arrangements, the employer sets a fixed monthly budget, and employees use that tax-free money to buy their own individual health insurance. For 2027, three things changed at once: the IRS raised the QSEHRA limits, the federal government renamed the ICHRA as the CHOICE Arrangement, and CMS removed a paperwork burden for account-based plans.
This guide to health reimbursement arrangements gives you the new 2027 numbers, a side-by-side comparison of the two main arrangements, and the three steps to set one up.
What Are Health Reimbursement Arrangements?
A health reimbursement arrangement (HRA) is an employer-funded plan that reimburses employees, tax-free, for qualified medical expenses — most often the premiums for individual health insurance — up to a fixed dollar amount per year.
The employer funds and owns the arrangement; employees do not contribute from their own pay. Unlike a group health plan, the employer does not pick one policy for everyone. Each employee buys the individual coverage that fits them and claims the money back.
Two arrangements matter most. The Qualified Small Employer HRA (QSEHRA) is for employers with fewer than 50 full-time-equivalent employees that offer no group health plan. The Individual Coverage HRA (ICHRA) — now the CHOICE Arrangement — can be offered by employers of any size with at least one employee who is not a self-employed owner or the owner’s spouse. A third, smaller type, the excepted benefit HRA, can sit alongside a group plan for costs such as copays and deductibles; its 2027 limit is $2,250 under IRS Rev. Proc. 2026-24.
What’s New for Health Reimbursement Arrangements in 2027?
New QSEHRA Limits for 2027
The IRS published the 2027 QSEHRA limits on November 5, 2026, in Rev. Proc. 2026-35, section 3.68: $6,700 for self-only coverage and $13,550 for family coverage, up from $6,450 and $13,100 in 2026. The full figures and rules are in the limits section below.
ICHRA Is Now the CHOICE Arrangement
On September 3, 2026, CMS and the SBA announced that the Individual Coverage HRA (ICHRA) is now the CHOICE Arrangement — short for Custom Health Option and Individual Care Expense. Nothing about the benefit changed for health reimbursement arrangements: the same 2019 ICHRA regulations still govern it, and employers already offering one need not change plan documents or payroll setups. One caution: the new name is not yet in federal law. A bill that would have written CHOICE into the tax code was changed before it was signed in July 2025, and a later House bill (H.R. 6703) was still waiting for Senate action. Use “CHOICE Arrangement (formerly ICHRA)” in your notices.
The Medicare Part D Notice Exemption
In a final rule issued in April 2026, CMS exempted account-based plans — including HRAs and ICHRAs — from the Medicare Part D creditable coverage disclosure requirements, effective for coverage beginning on or after January 1, 2027. These arrangements do not offer drug coverage directly; they reimburse premiums and expenses.
From 2027, their sponsors no longer have to determine or disclose creditable coverage status, or file the related disclosure with CMS. The exemption covers account-based plans only: a group plan that directly offers drug coverage must still send the notices, and the old rules stay in force through 2026.
2027 QSEHRA Limits in Detail
| Coverage | 2027 annual limit | 2027 monthly | 2026 annual limit |
|---|---|---|---|
| Self-only | $6,700 | $558.33 | $6,450 |
| Family | $13,550 | $1,129.17 | $13,100 |
The QSEHRA has strict rules. Your business must have fewer than 50 full-time-equivalent employees, must not offer any group health plan, and must offer the arrangement on the same terms to all full-time employees — amounts may vary only by age and family size.
Employees using health reimbursement arrangements must hold qualifying minimum essential coverage, such as a Marketplace plan, to receive the money tax-free. Give written notice to new employees when they become eligible and to current employees at least 90 days before each plan year. For a year starting January 1, 2027, that notice was due around October 3, 2026 — before the IRS published the 2027 caps. If the QSEHRA counts as affordable, the employee’s family cannot claim a premium tax credit.
ICHRA vs QSEHRA: Side-by-Side Comparison
| Feature | ICHRA (CHOICE Arrangement) | QSEHRA |
|---|---|---|
| Employer size | Any size, at least one eligible employee | Under 50 full-time-equivalent employees |
| Group health plan allowed? | Yes, for other employee classes | No — any group plan disqualifies it |
| Annual contribution cap | No federal cap | $6,700 self-only / $13,550 family in 2027 |
| Vary by employee class? | Yes — 10 permitted classes | No — same terms for all full-time employees |
| Vary by age or family size? | Yes, within limits (max 3:1 oldest to youngest) | Yes, by age and family size |
| Employee must have own coverage? | Yes — individual coverage or Medicare | Yes — qualifying minimum essential coverage |
| Premium tax credit | No credit if the offer is affordable (2027: 10.22%) | No credit if the QSEHRA is affordable |
| Best for | Larger employers, or mixed group-plan/HRA setups | Small employers with no group plan |
 The affordability test matters for both types of health reimbursement arrangements.
For a CHOICE Arrangement in 2027, the offer is affordable if the employee’s monthly cost for the self-only, lowest-cost Silver plan in their area — after your reimbursement — is less than 10.22% of one-twelfth of their yearly household income (IRS Rev. Proc. 2026-26). If affordable, no premium tax credit is allowed, even if the employee declines. If not affordable, the employee can choose the arrangement or the tax credit, but not both.
How to Set Up a Health Reimbursement Arrangement in 3 Steps
Step 1: Choose the arrangement and the amount. Pick the QSEHRA if you have fewer than 50 full-time-equivalent employees and no group plan; pick the ICHRA/CHOICE Arrangement if you are larger, or want to keep a group plan for one class of employees and offer the arrangement to another.
Set the contribution using the 2027 caps above for a QSEHRA, or your budget and local premiums for a CHOICE Arrangement. Decide what you will reimburse — premiums only, or premiums plus other qualified medical expenses — and whether dependents are included.
Step 2: Put it in writing and give the required notice. Adopt a written plan document stating the eligibility rules, the reimbursement amount, and which expenses qualify. Then send the employee notice on time: at least 90 days before the plan year starts (or as soon as a new employee becomes eligible). It must state the amount offered, the start date, and that the employee must have individual coverage to use the money.
HealthCare.gov and CMS publish sample letters you can adapt, and most employers use a third-party administrator for the paperwork and reimbursements.
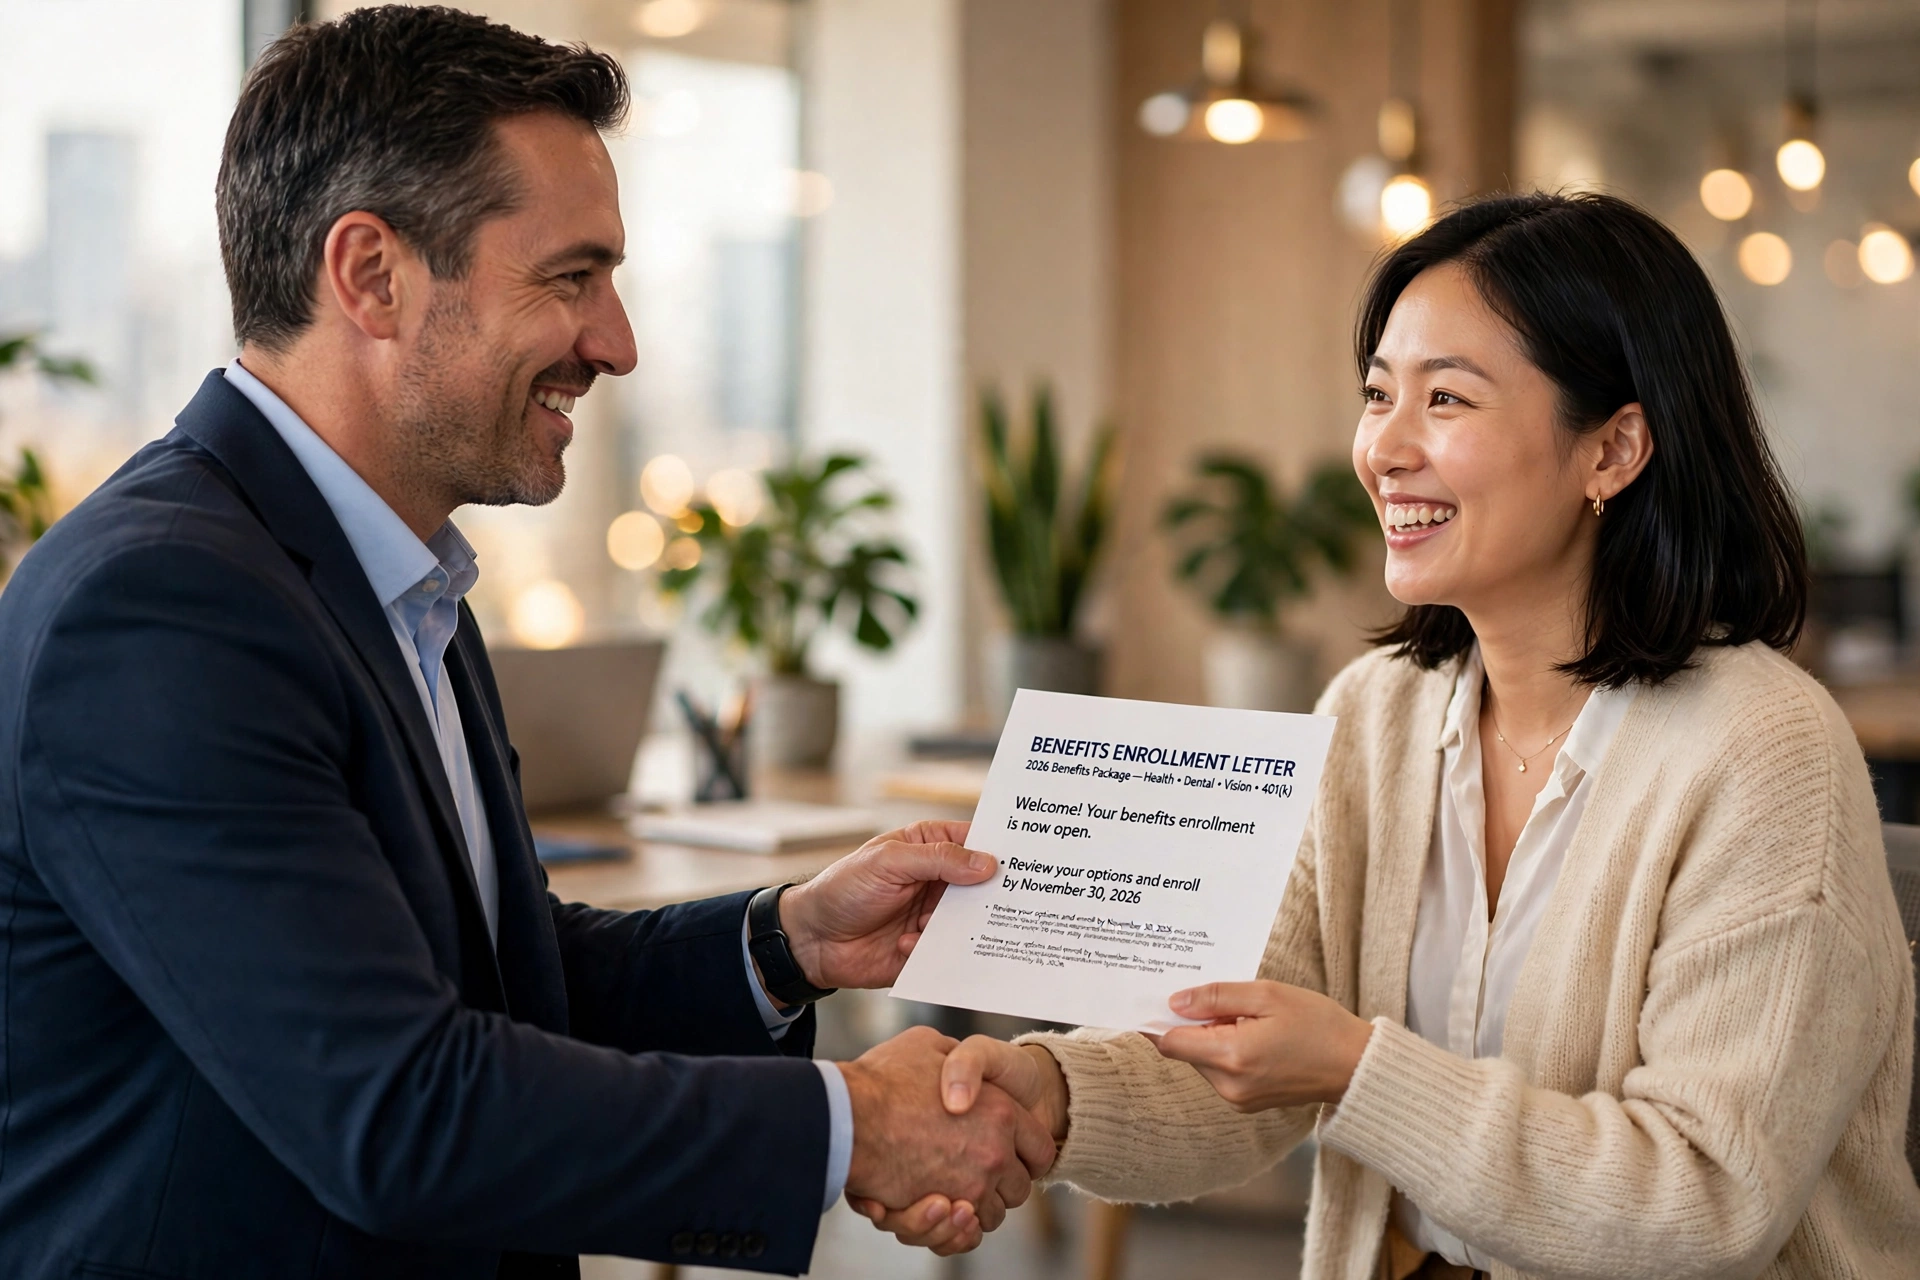 Step 3: Help employees enroll and claim. Employees must enroll in individual health insurance — a Marketplace plan, an off-exchange plan, or Medicare — before the arrangement starts, and a CHOICE Arrangement offer can qualify them for a Special Enrollment Period outside open enrollment.
Tell them to keep the offer letter for the Marketplace application. Employees then submit proof of their premium or expense, and you reimburse up to the agreed amount. Remind them that health reimbursement arrangements pay tax-free only while they hold qualifying coverage, and that accepting an affordable offer means giving up the premium tax credit.
Who Should Pick Which Arrangement?
A business with under 50 employees and no group plan should usually start with the QSEHRA: it is the simplest option, and the 2027 caps can cover a large share of a Marketplace premium. A business with 50 or more employees, or one that wants to keep a group plan for some staff, needs the ICHRA/CHOICE Arrangement, because the QSEHRA is closed to it.
Employers with staff in several states often prefer health reimbursement arrangements such as the CHOICE Arrangement too, since employees pick their own local plan. Whatever you choose, check the affordability math first: a contribution that looks generous can still leave an employee worse off than the premium tax credit. For help choosing between plan types, see our guide to PPO vs HMO plans.
Frequently Asked Questions
What is the 2027 QSEHRA limit?
$6,700 for self-only coverage and $13,550 for family coverage (IRS Rev. Proc. 2026-35, section 3.68) — about $558.33 and $1,129.17 a month. The 2026 limits were $6,450 and $13,100.
Is ICHRA now called the CHOICE Arrangement?
Yes. On September 3, 2026, CMS and the SBA renamed the Individual Coverage HRA (ICHRA) as the CHOICE Arrangement. Only the name changed; the rules did not, and the name is not yet in federal law.
Can a small employer offer an HRA and a group health plan?
It depends. A QSEHRA cannot be offered alongside any group health plan. A CHOICE Arrangement can cover one employee class while another class keeps a group plan, but the same employees cannot be offered both.
Do HRAs still have to send Medicare Part D notices in 2027?
No. A CMS final rule from April 2026 exempts account-based plans, including HRAs and ICHRAs, from the Part D creditable coverage disclosures for coverage beginning on or after January 1, 2027. Group plans that offer drug coverage directly must still send them.
Can an employee get a premium tax credit and an HRA?
Not both. If the HRA offer is affordable, no premium tax credit is allowed. If it is not affordable, the employee may take the tax credit instead — but must decline the arrangement.
The Bottom Line
For 2027, health reimbursement arrangements got more room and less paperwork: QSEHRA limits rose to $6,700 self-only and $13,550 family, the ICHRA gained the clearer CHOICE Arrangement name, and the Part D notice duty disappears for account-based plans from January 1, 2027. The right choice is still a math problem — compare your contribution against local premiums and the 10.22% affordability threshold, and send the notice at least 90 days before your plan year starts.
Disclaimer: This article is general information about health reimbursement arrangements in the United States for 2027. It is not tax, legal, or financial advice, and it is not a quote. Limits, rules, and deadlines change, and individual circumstances vary. Confirm current requirements with the IRS, CMS, or HealthCare.gov, and talk to a licensed tax professional or benefits adviser before setting up an arrangement.



2 Comments on “Health Reimbursement Arrangements 2027: New Limits”